Best Joint Bank Account UK (2026): Top 7 Rated for Bills, Savings
Last Updated on
The best joint bank account UK options in 2026 depend entirely on how you and your partner manage household finances.
Modern shared accounts balance digital convenience with financial perks, offering automated bill-splitting apps, cashback on utility bills, or traditional high-street banking access.
Choosing the right provider streamlines multi-person financial management while protecting your credit profile.
What Is a Joint Bank Account?
A joint bank account is a shared current or savings account opened by two or more individuals, granting all parties equal legal rights to deposit, withdraw, and manage the funds.
Under UK law, any money paid into the account automatically becomes the joint legal property of all signatories. When you open a shared account in the UK, individual ownership over the deposited money ceases.
Regardless of who earns the income, initiates the transfer, or sets up the most deposits, the law treats the funds as a single pool owned 100% by both parties simultaneously. Understanding this dynamic is crucial before combining day-to-day cash flows.
What Are the Best Joint Bank Accounts in the UK?
The best joint bank account UK providers are split into two distinct categories: agile digital-first challenger apps and established high-street banking institutions.
Digital-first banks prioritise instant push notifications, algorithmic budgeting categories, and virtual card issuance. High-street banks focus on branch networks, switching bonuses, and integrated insurance bundles.
Additionally, tech-forward couples managing diverse modern assets alongside their everyday money often look for integrations with fintech platforms or specialised Crypto-friendly banks to balance traditional household spending with digital asset allocations.
Below is an at-a-glance comparison of our top-rated UK joint accounts for 2026. Scroll down for in-depth reviews, pros, cons, and hidden fees across all 10 major providers.
| Bank Account | Best For | Monthly Fee | Key Standout Feature | Overdraft / Credit Impact |
|---|---|---|---|---|
| Starling Bank Joint | Modern App Budgeting | £0 | Virtual cards for shared bills + Spaces | Arranged overdraft available; creates financial association |
| Monzo Joint Account | Multiple Shared Pots | £0 | Shared Pots, automatic bill sorting | No joint overdraft (protects credit files from mutual debt) |
| Santander Edge | Utility Cashback | £3 | 1% cashback on monthly household bills & travel (up to £20/mo) | Arranged overdraft available; creates financial association |
| First Direct 1st Account | Customer Service & Regular Saver | £0 | £250 interest-free overdraft buffer + access to 7% regular saver | Arranged overdraft; creates financial association |
| NatWest Select | High-Street Switching Bonus | £0 | Periodic £175+ switch offers + access to digital regular saver | Arranged overdraft; creates financial association |
| Nationwide FlexDirect | Fixed In-Credit Interest | £0 | 5% AER fixed on balances up to £1,500 for year 1 | Arranged overdraft; creates financial association |
| Club Lloyds | Lifestyle Perks & Cinema Tickets | £3 (waived if £2,000 paid in/mo) | Annual Disney+, cinema tickets, or magazine subscription | Arranged overdraft; creates financial association |
1. Starling Joint Account
The Starling Joint Account is the UK’s best fee-free digital shared account, combining zero foreign transaction fees on overseas spending and ATM cash withdrawals with an automated Bills Manager feature that ring-fences fixed household overheads into dedicated virtual spaces.
-
Bills Manager: Automatically moves fixed bill amounts into separate digital Spaces to safeguard your primary balance from accidental spending.
-
Zero Overseas Fees: Eliminates standard foreign transaction charges and international ATM withdrawal fees when holidaying or shopping abroad.
-
Instant Alerts: Dispatches real-time push notifications to both smartphone devices simultaneously, the exact microsecond a card transaction occurs.
2. Monzo Joint Account
The Monzo Joint Account is the top choice for algorithmic budgeting tools, allowing couples to track combined outgoings, automate cost-splitting, and tag retail purchases while earning competitive interest via shared instant-access savings pots directly managed from a unified mobile app ecosystem.
-
Shared Savings Pots: Earns competitive interest rates on pooled funds within customised, ring-fenced growth folders inside the core application.
-
Algorithmic Categorisation: Automatically models, sorts, and tags daily outgoings into discrete labels like Groceries or Entertainment with weekly financial summaries.
-
Auto-Splitting: Allows a single tap inside the user interface to instantly split the cost of independent tabs paid on a solo debit card.
3. Santander Edge Current Account
The Santander Edge Joint Account ranks as the best shared account for monthly cashback rewards, offering couples a structured framework to earn 1% back on essential supermarket spending and 1% back on qualifying monthly household utility bills like council tax, broadband, and energy.
-
1% Bills Cashback: Provides a 1% direct financial rebate (capped at £10 monthly) on qualifying household utility variable direct debits.
-
1% Essentials Cashback: Delivers an additional 1% financial rebate (capped at £10 monthly) on regular supermarket shopping trips and transit costs.
-
Account Parameters: Requires a standard £3 monthly account maintenance fee and a minimum cumulative monthly deposit of £500 to sustain rewards.
4. First Direct
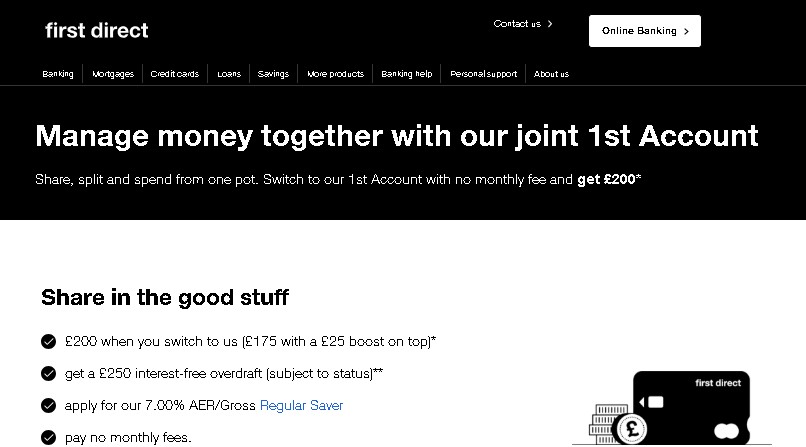
The First Direct 1st Account is the industry leader for exceptional 24/7 human customer support, providing joint applicants with an interest-free £250 arranged overdraft safety net buffer alongside exclusive digital access to a high-yield, market-leading 7% AER fixed regular savings account.
-
Award-Winning Support: Provides permanent, unrestricted access to highly rated 24/7 UK-based telephone and digital customer service networks.
-
Fee-Free Buffer: Offers an arranged overdraft facility equipped with an interest-free buffer zone up to £250 for eligible household credit profiles.
-
7.00% Regular Saver Access: Unlocks exclusive secondary entry into a market-leading 7% AER fixed-rate regular savings framework for both applicants.
5. Nationwide FlexDirect
The Nationwide FlexDirect account is the best high-street option for maximising in-credit interest on pooled balances, yielding a competitive 5.00% AER fixed interest rate on shared funds up to £1,500 for the first year, alongside introductory everyday debit card shopping incentives.
-
5.00% AER In-Credit Interest: Yields a fixed 5% interest rate on pooled everyday balances up to £1,500 during the introductory 12-month period.
-
1% Cashback on Spending: Pays a 1% direct cash rebate on standard daily debit card transactions during the first calendar year (capped at £5 monthly).
-
Switching Incentives: Deploys highly competitive introductory cash incentives via the official Current Account Switch Service (CASS) for new switching couples.
6. TSB Spend & Save
The TSB Spend & Save account is a highly versatile option optimised for multi-person households and student shared living status, allowing up to five unique cohabitants to be named on one joint account mandate for transparent, shared utility bill and rental tracking.
-
Multi-Holder Friendly: Permits up to five individual holders on a single account mandate (requires branch setup for three or more applicants), making it ideal for student flats and shared houses.
-
£5 Monthly Cashback: Yields a predictable £5 cash reward each month for the first half-year if both users achieve 20 distinct monthly debit card payments.
-
Save the Change: Automatically rounds up point-of-sale transactions to the nearest whole pound, micro-transferring the residual spare change into savings.
7. NatWest
The NatWest Reward account provides couples with straightforward digital financial cash perks, delivering a net £2 monthly payout for maintaining two active utility Direct Debits alongside additional monetary login incentives and up to 15% retail cashback at partner high-street retailers.
-
£2 Net Monthly Reward: Generates a net £2 financial bonus every month for maintaining two active, separate utility or service Direct Debits.
-
Digital Login Bonus: Credits an extra £1 monthly sum simply for executing a standard login into the native mobile banking portal once a month.
-
Retailer Cashback: Unlocks up to 15% variable merchant cashback when processing transactions at verified national retail partners.
8. Lloyds Bank
The Club Lloyds account serves as a premium lifestyle-focused joint banking package, trading a waivable monthly fee for annual entertainment perks such as a Disney+ subscription or free cinema tickets, alongside a tiered in-credit interest structure for larger household balance deposits.
-
Annual Entertainment Perk: Grants a choice of one yearly entertainment perk, including standard streaming subscriptions or multi-pack commercial cinema tickets.
-
Tiered Interest Structure: Accrues internal credit interest directly on day-to-day transaction balances when maintaining stable larger deposit volumes.
-
Fee Waiver Capability: Completely eliminates the standard £3 monthly account maintenance fee if a cumulative £2,000 enters the account each month.
9. HSBC
The HSBC Advance account is tailored for global travellers seeking secure, multi-channel branch banking networks, offering couples fee-free international money transfers across worldwide HSBC accounts and access to a premium consumer rewards platform with zero monthly account upkeep fees.
-
Global Money Transfers: Executes fast, fee-free international currency movements across internal, worldwide HSBC consumer accounts.
-
Home & Away Platform: Delivers programmatic access to exclusive domestic and international shopping, hospitality, and dining retail discounts.
-
No Monthly Maintenance Fee: Pairs full, unrestricted entry into physical high-street branch infrastructure with zero standard monthly upkeep costs.
10. Revolut Joint Account
The Revolut Joint Account is suited for cross-border couples needing multi-currency spending across 30+ currencies with real-time app notifications and disposable virtual cards.
-
Multi-Currency Vaults: Convert and store foreign currencies at low-margin exchange rates for international travel and joint overseas expenses.
-
Revolut Pockets: Automatically allocate recurring shared commitments and subscriptions away from your primary spend balance.
-
FSCS Clarification: Revolut UK deposits are protected via regulatory safeguarding accounts rather than the statutory £85k/£170k FSCS scheme.

Can a Salary Account Be a Joint Account?
Yes, your salary account can be a joint account. In the UK, employers do not require a sole personal account to process payroll.
As long as you provide your employer with the correct 6-digit sort code, 8-digit account number, and the exact registered name on the account, direct deposits via BACS or Faster Payments will clear normally.
Things to Keep in Mind When Depositing Salary into a Joint Account:
-
HMRC & Income Tax: Direct salary deposits into a joint account do not alter your individual income tax liability. HMRC taxes each earner based on their personal National Insurance number and PAYE tax code, not where the funds land.
-
Personal Savings Allowance (PSA): Any interest earned on joint funds is split 50/50 for tax purposes unless you formally declare an alternative beneficial split to HMRC via Form 17.
-
Loss of Financial Privacy: Once your salary clears into a joint account, the other account holder has immediate legal ownership of those funds and can withdraw, transfer, or spend the balance in full without your separate consent.
Best Joint Accounts with Multiple Savings Pots
If you and your partner want to organise funds for household bills, annual holidays, emergency reserves, and mortgage deposits in one place, choosing an account with sub-accounts or “pots” is essential.
Monzo Shared Pots
Monzo allows two individuals with existing Monzo profiles to open a Joint Account and create dedicated Shared Pots:
- Bill-Splitting Automation: You can assign specific Direct Debits and standing orders to withdraw directly from individual pots rather than your main balance.
- Joint Interest Pots: Monzo offers interest-earning savings pots backed by third-party partner banks, allowing both of you to pool cash toward high-yield goals.
Starling Bank “Spaces”
Starling provides virtual partitioning through Saving Spaces:
- Interactive Targets: Set visual deadlines and track mutual contributions.
- Virtual Connected Cards: Starling lets you connect a dedicated virtual card to a specific “Bills Space,” ensuring utility payments never eat into your day-to-day shopping funds.
Chase UK (Multiple Linked Saver Accounts)
While Chase does not yet offer a native multi-user joint current account, couples frequently use Chase by opening up to 10 distinct, fee-free saver accounts under one roof to track separate budget lines alongside their 1% everyday cashback feature.
How to Open a Joint Savings Account Online
Opening a joint savings account online takes between 10 and 15 minutes through modern UK banking platforms.
Step-by-Step Online Application Process:
- Confirm Eligibility: Both applicants must be UK residents, aged 18 or older, and reside at the same residential address (some traditional providers allow different addresses, but digital banks like Monzo and Starling require both individuals to hold verified personal accounts first).
- Gather Required Documents:
- Valid photo ID (UK Driving Licence or Passport).
- 3-year UK address history.
- Proof of address (recent utility bill, council tax bill, or bank statement dated within the last 3 months).
- Submit the Digital Application:
- App-based banks (Starling/Monzo): Person A initiates the request inside the app and sends an in-app invite to Person B. Person B accepts, confirms their details, and verification completes via facial biometrics.
- High-Street banks (Santander/NatWest): One applicant begins the online web application and enters the co-applicant’s details. An invitation link is emailed to the second party to verify their identity remotely.
- Identity & Credit Checks: The provider runs an automated identity check and a soft credit check (or hard check if an overdraft facility is requested).
- Fund the Account: Once approved, transfer funds using Faster Payments. Both account holders receive their own debit cards within 3 to 5 working days.
Best Joint Accounts According to MoneySavingExpert (MSE) Rules
Financial expert Martin Lewis and the MoneySavingExpert (MSE) community evaluate joint accounts based on one golden rule: separate your daily spending from shared household liabilities.
Core MSE Joint Account Principles:
-
Use the “Bills Only” Method: Rather than pooling all personal earnings, MSE strongly advocates keeping individual sole accounts for discretionary spending and setting up a separate joint account purely for shared household outgoings (rent/mortgage, utilities, council tax, groceries).
-
Never Open a Joint Overdraft with Housemates: When you open a joint account with an overdraft facility, credit reference agencies (Experian, Equifax, TransUnion) create a Financial Association. If your flatmate or partner has an adverse credit history, their score will drag down your mortgage or personal loan eligibility.
-
Maximise Switch Cash: Couples can make the most of the Current Account Switch Service (CASS) by switching a joint account between banks offering cash bonuses (e.g., NatWest, First Direct), earning hundreds of pounds in free cash incentives.
-
Double FSCS Limits: MSE regularly reminds savers that joint accounts carry double the standard FSCS safety protection—covering up to £170,000 against institutional default.
What Happens to Your Credit Score? (The Financial Association Trap)
Opening a joint account with an overdraft facility creates a formal Financial Association between you and the co-holder across the three primary UK credit reference bureaus:
-
Shared Liability: Both parties are bound by “joint and several liability.” If one person runs up a £1,500 unarranged overdraft, the bank can pursue either person for 100% of the debt.
-
Credit Contagion: If your co-holder misses credit card payments, enters an IVA, or defaults elsewhere, their poor credit profile will be visible during any future lending checks you make.
-
How to Sever the Link: If you split up or change living arrangements, you must formally close the account and file a Notice of Disassociation with Experian, Equifax, and TransUnion to detach your credit files.
How Does a Joint Bank Account Work?
Standard UK joint accounts operate under a “one-to-sign” mandate by default. This allows either individual to independently withdraw funds, set up Direct Debits, or utilise an arranged overdraft without the other person’s prior authorisation.
An alternative “all-to-sign” mandate exists primarily for business arrangements or formal dispute management, requiring joint authorisation on every outgoing transaction. Note that under a standard one-to-sign mandate, banks are not liable if one account holder drains the balance.
Can You Convert a Personal Bank Account to a Joint One?
Yes, you can convert a personal bank account to a joint one at most UK high-street banks by completing an add-a-person process. The existing holder invites the second individual, who must pass standard identity, address, and credit checks before a second debit card is issued.
While traditional institutions like NatWest, Lloyds, and Barclays allow a seamless transition from a sole account to a joint account, the operational process differs for mobile-first challenger banks.
Note: Some digital-first challenger banks do not allow sole-to-joint conversions. Instead, they require both users to hold individual accounts first, then open a completely separate, brand-new joint account within the app.
Pros and Cons of a Joint Bank Account
Before choosing the best joint account for couples and merging your financial pipelines, it is essential to weigh the daily operational conveniences against the long-term legal and credit risks.
Pros
-
Streamlined Household Management: Simplifies paying for shared fixed overheads like mortgages, rent, council tax, and utility bills from one central pool.
-
Enhanced Savings Milestones: Combining capital into a single joint savings pot makes it easier to hit targets faster while maintaining shared visibility.
-
Dual FSCS Protection: For joint accounts, the Financial Services Compensation Scheme (FSCS) protection doubles, covering up to £170,000 (£85,000 per person) if the institution fails.
-
Uninterrupted Access (Right of Survivorship): If one account holder passes away, the account does not get frozen for probate. Under UK law, 100% legal ownership and access automatically pass to the surviving partner immediately.
Cons
-
Mutual Debt Exposure: Under joint and several liability, you are personally liable for 100% of any overdraft balance, even if your partner spent the money alone.
-
Credit File Association: You become formally linked on Experian, Equifax, and TransUnion files, meaning your partner’s missed payments can harm your creditworthiness.
-
Zero Spending Privacy: Every point-of-sale purchase, standing order, and cash withdrawal is fully visible to both parties on live statements.
-
Mutual Consent on Closure: You cannot easily close a joint account without the other party’s agreement, and any balance in negative figures must be paid off first.
What Happens to a Joint Account If a Partner Dies?
Under UK law and the principle of the Right of Survivorship, a joint bank account is not frozen upon the death of one holder. Full legal ownership and operational control automatically pass directly to the surviving account holder.
-
Uninterrupted Access: The surviving partner retains continuous access to funds for utility bills and daily spending without waiting for probate.
-
Bank Notification: Inform the bank promptly with the death certificate so they can reissue single-named cards and update the account mandate.
-
Sole Accounts vs Joint Accounts: While joint accounts remain open, individual sole accounts held by the deceased are frozen immediately for probate estate distribution.
How to Choose the Best Bank to Open a Joint Account UK?
To choose the best joint bank account in the UK, weigh digital feature requirements against high-street financial perks.
Select a digital-first platform like Monzo or Starling for advanced mobile budgeting, or choose an institutional option like Santander or First Direct if you want to optimise your returns through bill cashback.
Always remember that opening a joint account creates a financial link between both partners’ credit files, making shared financial transparency essential.
FAQ
What is the best UK bank for joint savings account goals?
The best bank for joint savings focuses on maximising yield through competitive interest rates. Providers like Nationwide and specialised online savings apps offer dedicated joint savings accounts that allow both partners to accumulate interest collectively under the protection of the Financial Services Compensation Scheme (FSCS).
Which UK bank has the best customer satisfaction ratings for joint accounts?
Based on independent customer satisfaction reviews from Fairer Finance, First Direct consistently ranks as a top choice. Consumers value their 24/7 UK-based telephone support, reliable app stability, and clear, transparent terms for everyday banking.
Can you open a basic joint bank account with a poor credit score?
Yes. High-street institutions such as Barclays, Lloyds, and NatWest offer basic joint current accounts. These accounts do not include an arranged overdraft facility, removing the need for a hard credit check and making them accessible to partners focusing purely on bill management.
Can you open a UK joint bank account online without paperwork?
Yes, digital challengers like Starling Bank and Monzo allow couples to open an online joint account with no physical paperwork. The entire process, including identity verification via video selfie and document scanning, is handled directly within the mobile application.